
A native app for the Walmart Rewards Mastercard.
Built for everyday, designed for the app that doesn't exist yet.
The Walmart Rewards Mastercard has no dedicated app - cardholders are missing the basics: push notifications, biometric login, instalment tracking, and a real way to dispute a charge online. This project designs that native app, built around a smarter home screen and streamlined day-to-day flows.
- Research - collected complaints from online forums, and ran interviews and surveys with real cardholders.
- Benchmarking - analyzed 5–6 Canadian banking apps to decide what to borrow and what to leave out.
- UX - used the MoSCoW method to prioritize scope and structure the project.
- UI - built the visual system on Walmart's own brand guidelines, with a dedicated component design system.
- Prototype - a clickable prototype of 100+ screens with micro-interactions.
Walmart Credit Card and Mastercard holders · Weekly in-store and Walmart.com shoppers · People who carry a balance and watch due dates · Rewards earners who never get around to redeeming what they have.
What people run into vs. what the app answers with.
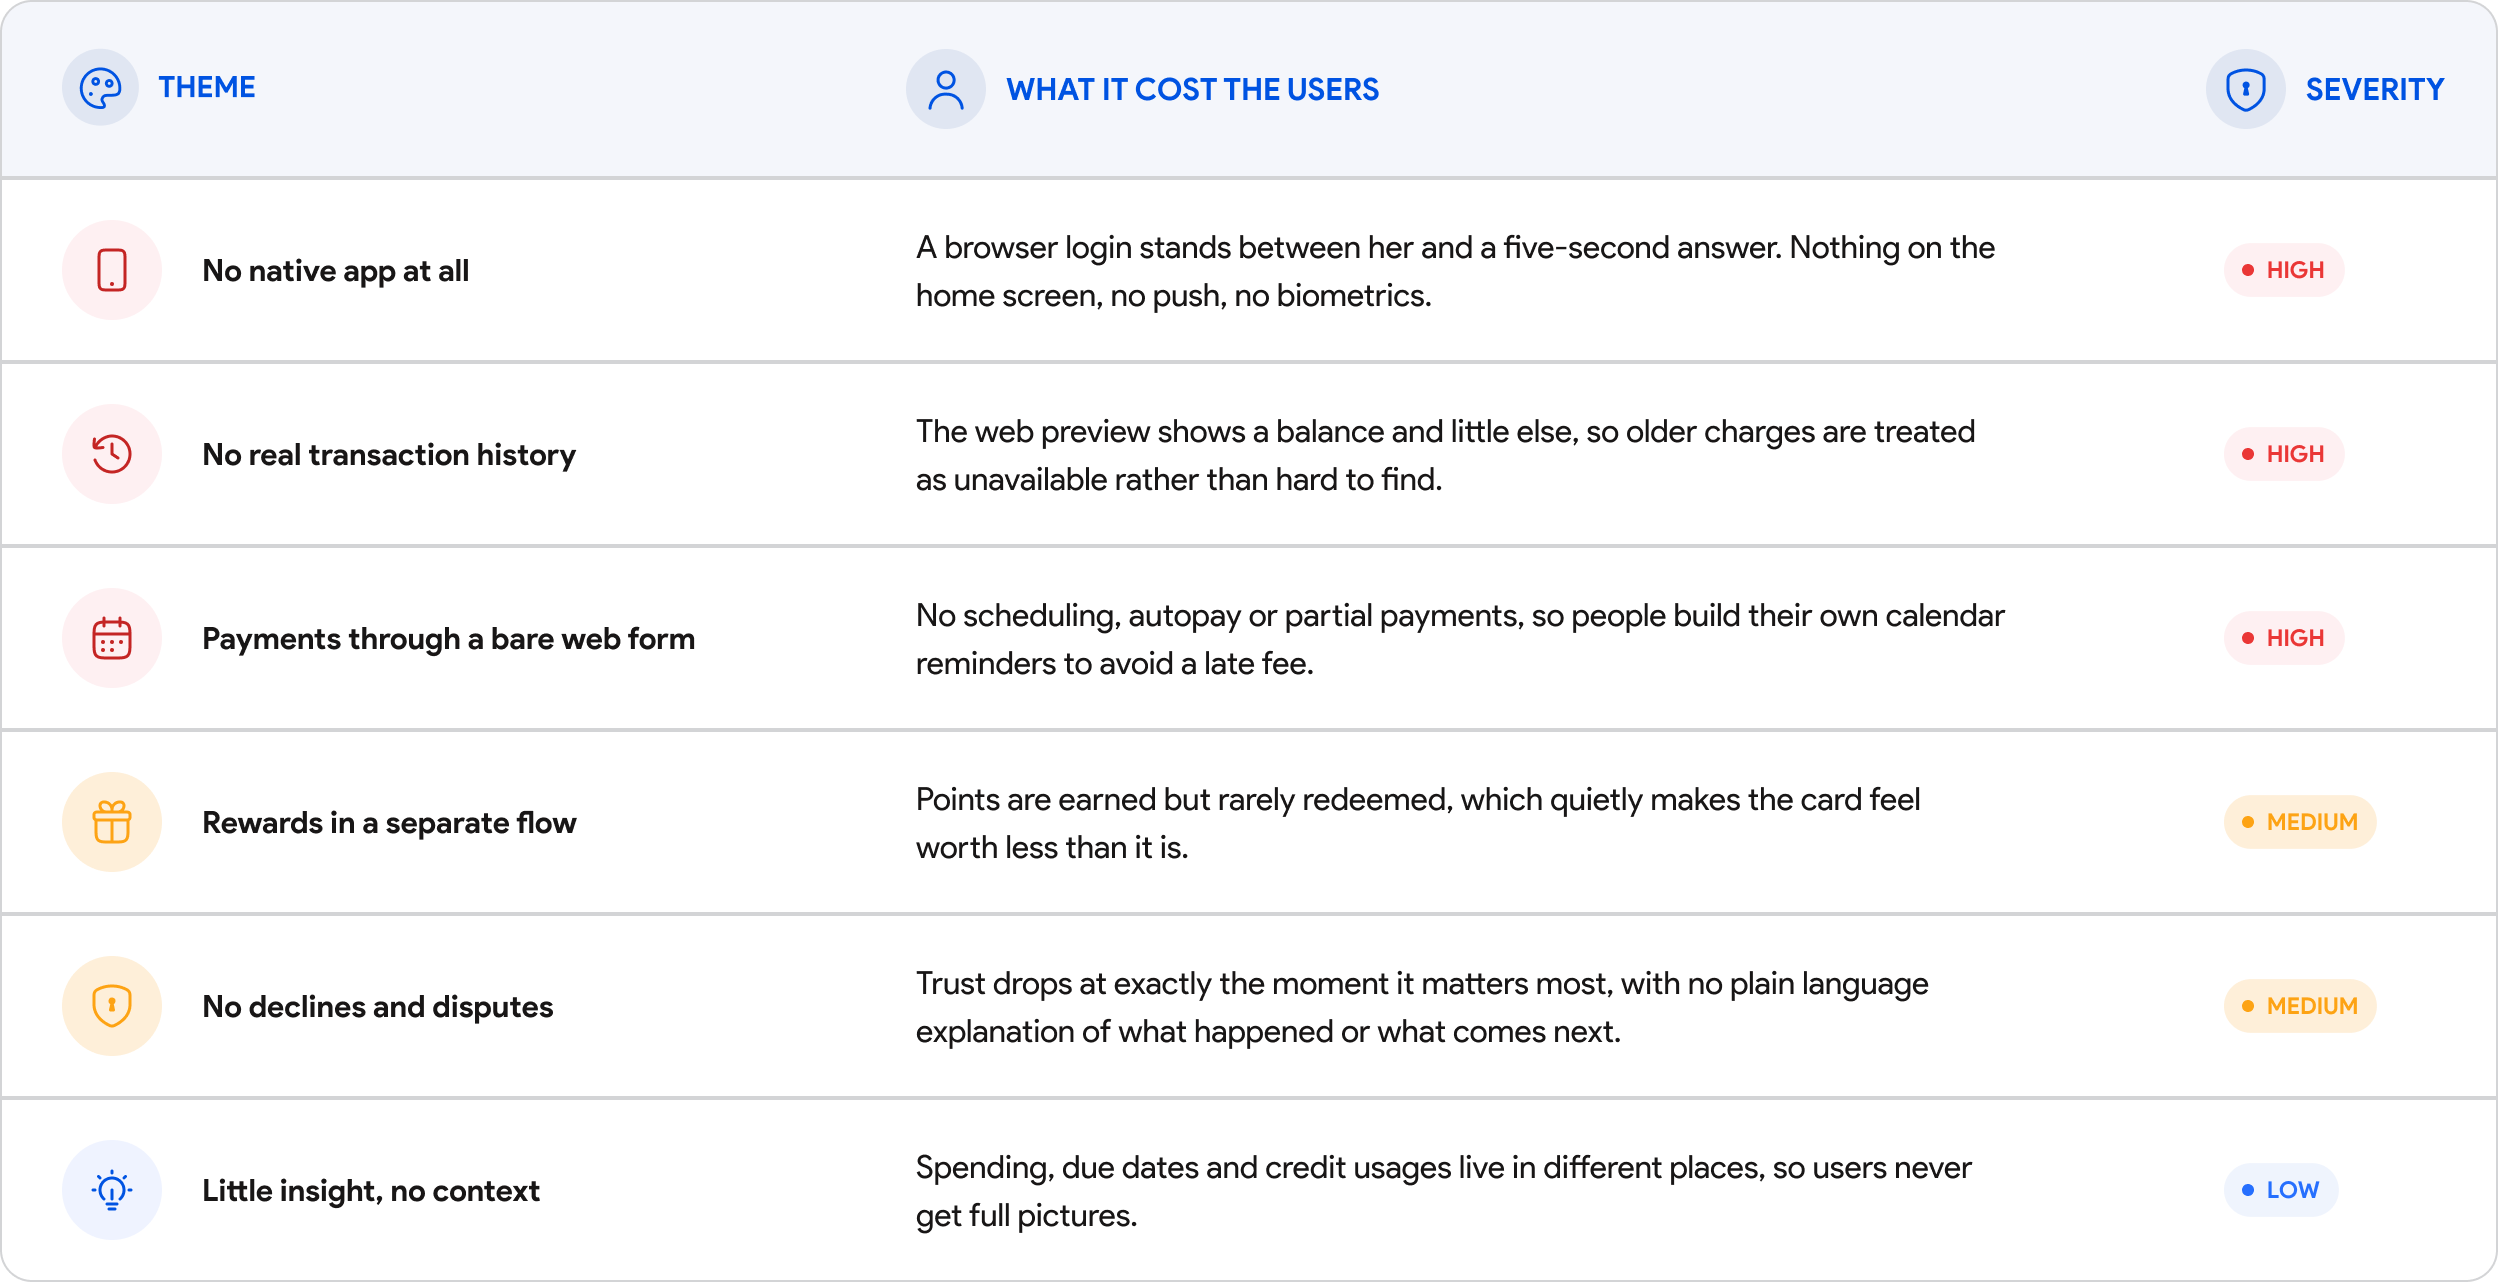
There was no app to review, so research started with real complaints across forums and customer service threads. Two root issues kept repeating: the friction of logging into a mobile browser, and how little account data is actually visible once inside.
What mattered wasn't the complaint - it was what it cost people.
With no official app to audit, desk research examined public sentiment across user forums, app reviews, and community threads. Each issue was weighed by its operational friction and frequency to determine release priority.
What people said in public, versus what they actually do.
We spoke to Walmart Credit Card holders in two settings: remote sessions with people who use the card weekly, and short intercepts outside a Walmart store, catching shoppers right after they'd paid.
Participants
10 Cardholders
Format
Remote + In-Store
Screening
Used card in last 30 days
Questions asked: How do you check your balance? How do you pay each month? How do you review older transactions? Have you seen unrecognized charges? Can you find your rewards balance? What do you want on the home screen?
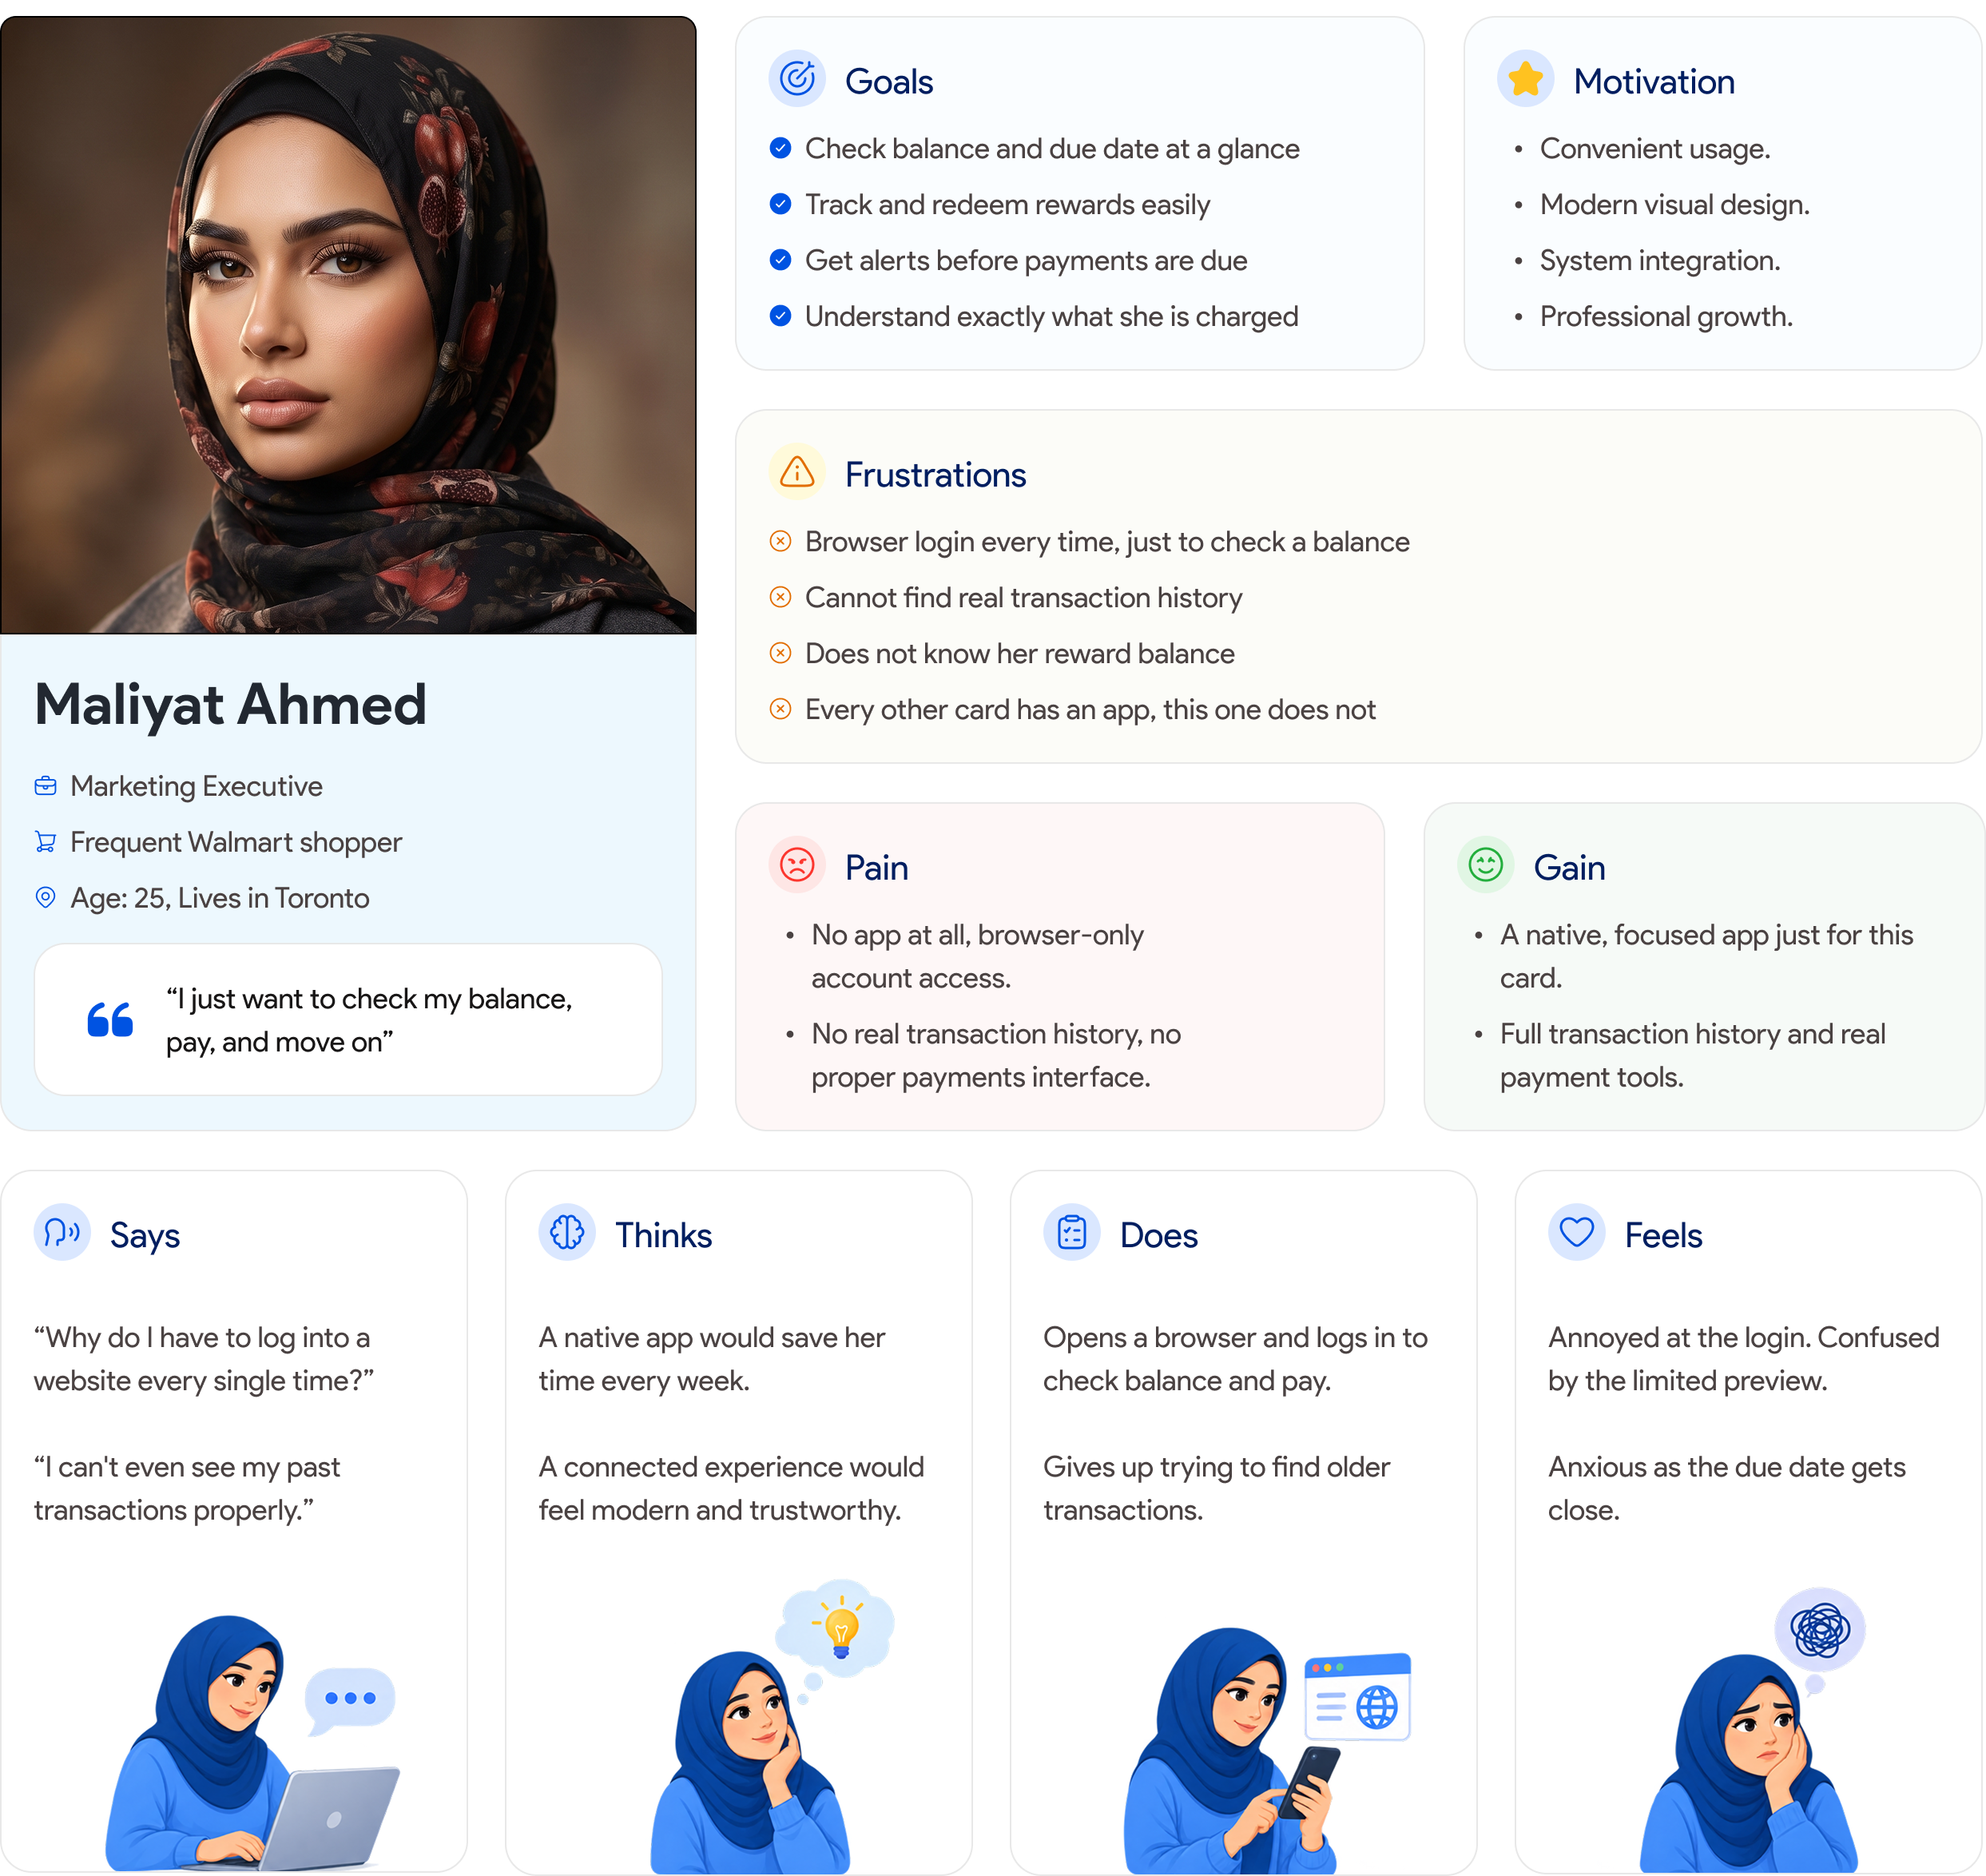
What we heard: most people couldn't recall their rewards balance. Everyone started at a browser, and most had the login saved in a password manager. Due dates were tracked outside the product entirely - calendar reminders, or the paper statement. Older transactions felt unavailable, not just hard to find.
One user carried the project.
Maliyat shops at Walmart most weeks, pays her card from her phone, and earns rewards she rarely gets around to spending. Every design decision was checked against whether it made her weekly check-in faster.
Everything in Must Have blocks a first release.
With a long list of possible features, we used the MoSCoW method to separate what the app must have from what it could wait for. Everything in Won't Have is a deliberate no for this phase, not an oversight.
Must Have
- Dedicated mobile app replacing browser-only access
- Balance and due date on the home screen
- Full, searchable transaction history
- In-app transaction disputes
- Biometric login for quick access
Should Have
- Flexible instalment terms
- Notification centre
- Real-time rewards tracking
- Push alerts for due dates and declines
- Autopay and payment scheduling
Could Have
- Live agent chat inside the app
- Digital receipt section in transaction details
- Spending insights by category
- Personalised Walmart offers and rewards
- Paperless statement preferences
Won't Have - This Phase
- In-app card lock and unlock
- Credit score monitoring and credit-building tools
- Full Walmart shopping / grocery ordering
- Broader budgeting and personal finance tools
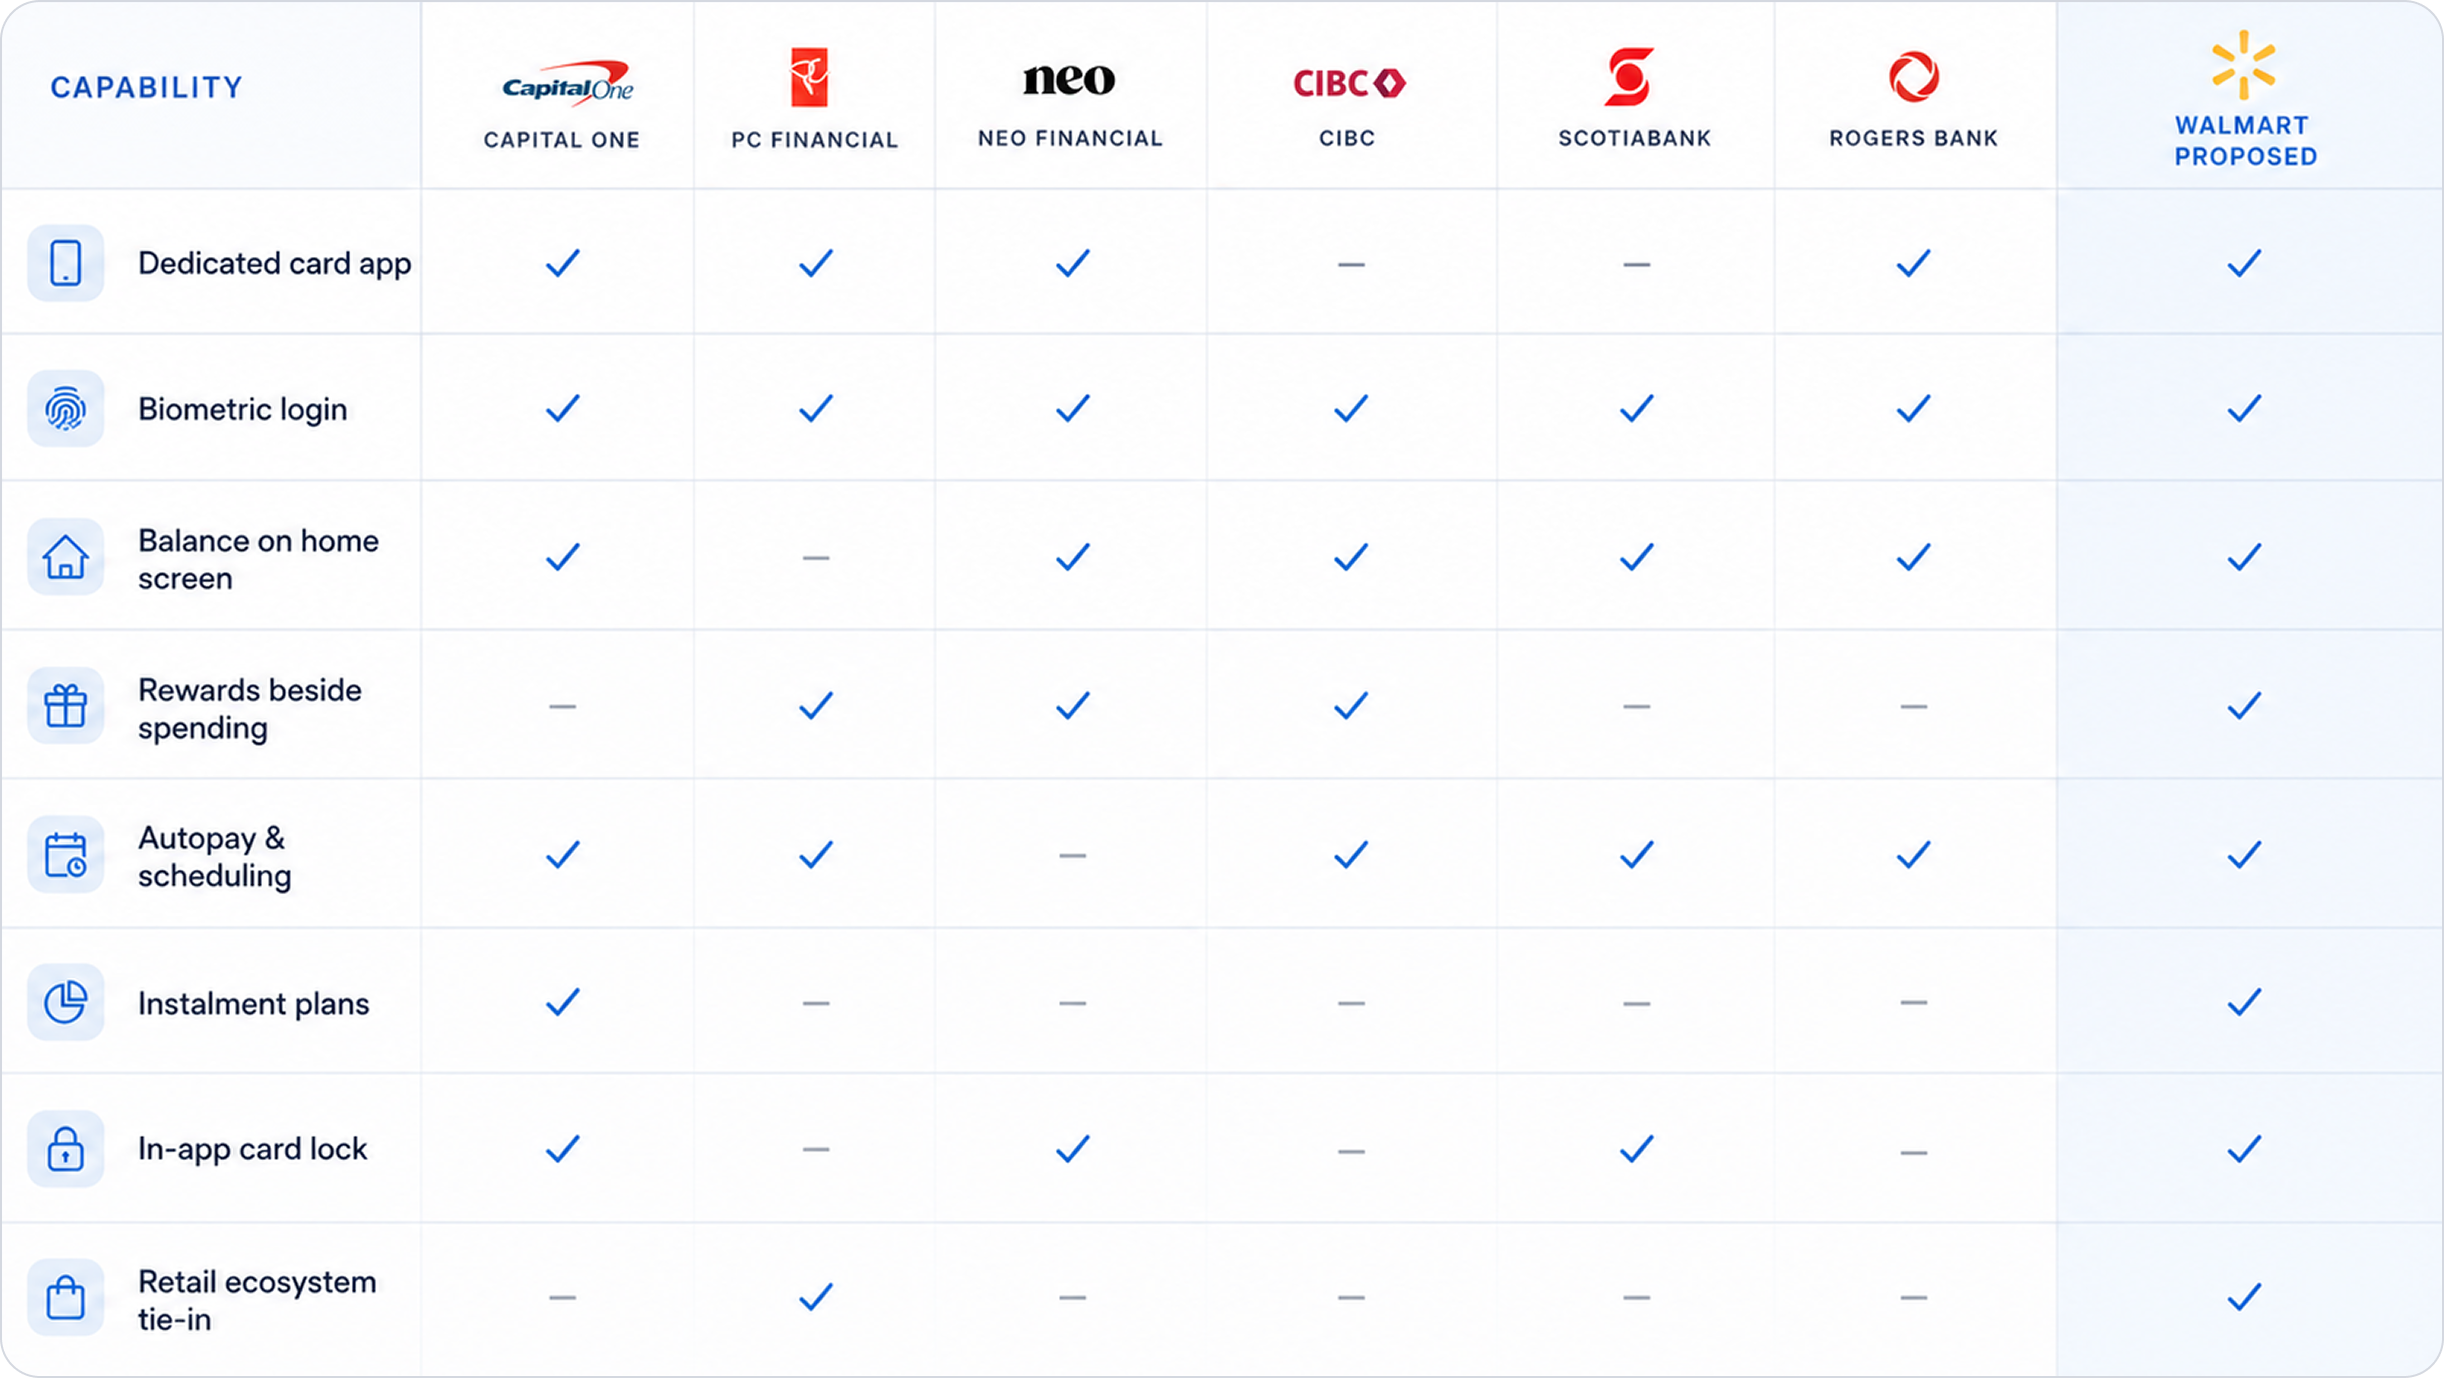
Benchmarked against six real apps, not just the obvious ones.
Six apps benchmarked across retail cards and full banking suites - Capital One, PC Financial, Neo Financial, CIBC, Scotiabank, and Rogers Bank - each reviewed for what works, what doesn't, and what it means for a Walmart-specific card experience.
Six journeys, mapped end to end.
Onboarding runs once and branches on a single question; everything after it is built for a returning user who wants the balance and nothing else. Each of the four core tasks lands on an explicit confirmation - the moment a payment or dispute leaves your hands is the moment people most want to be told what happened.

Structure, settled before a single brand colour went down.
The question at this stage was only hierarchy: what sits above the fold, how far the balance is from the pay button, and how many taps stand between a transaction and a dispute. Eight screens: Splash, Active Card, Home, Transactions, Transaction Details, Chat, Rewards, More.

Built on Walmart's guidelines, elevated for native mobile fintech.
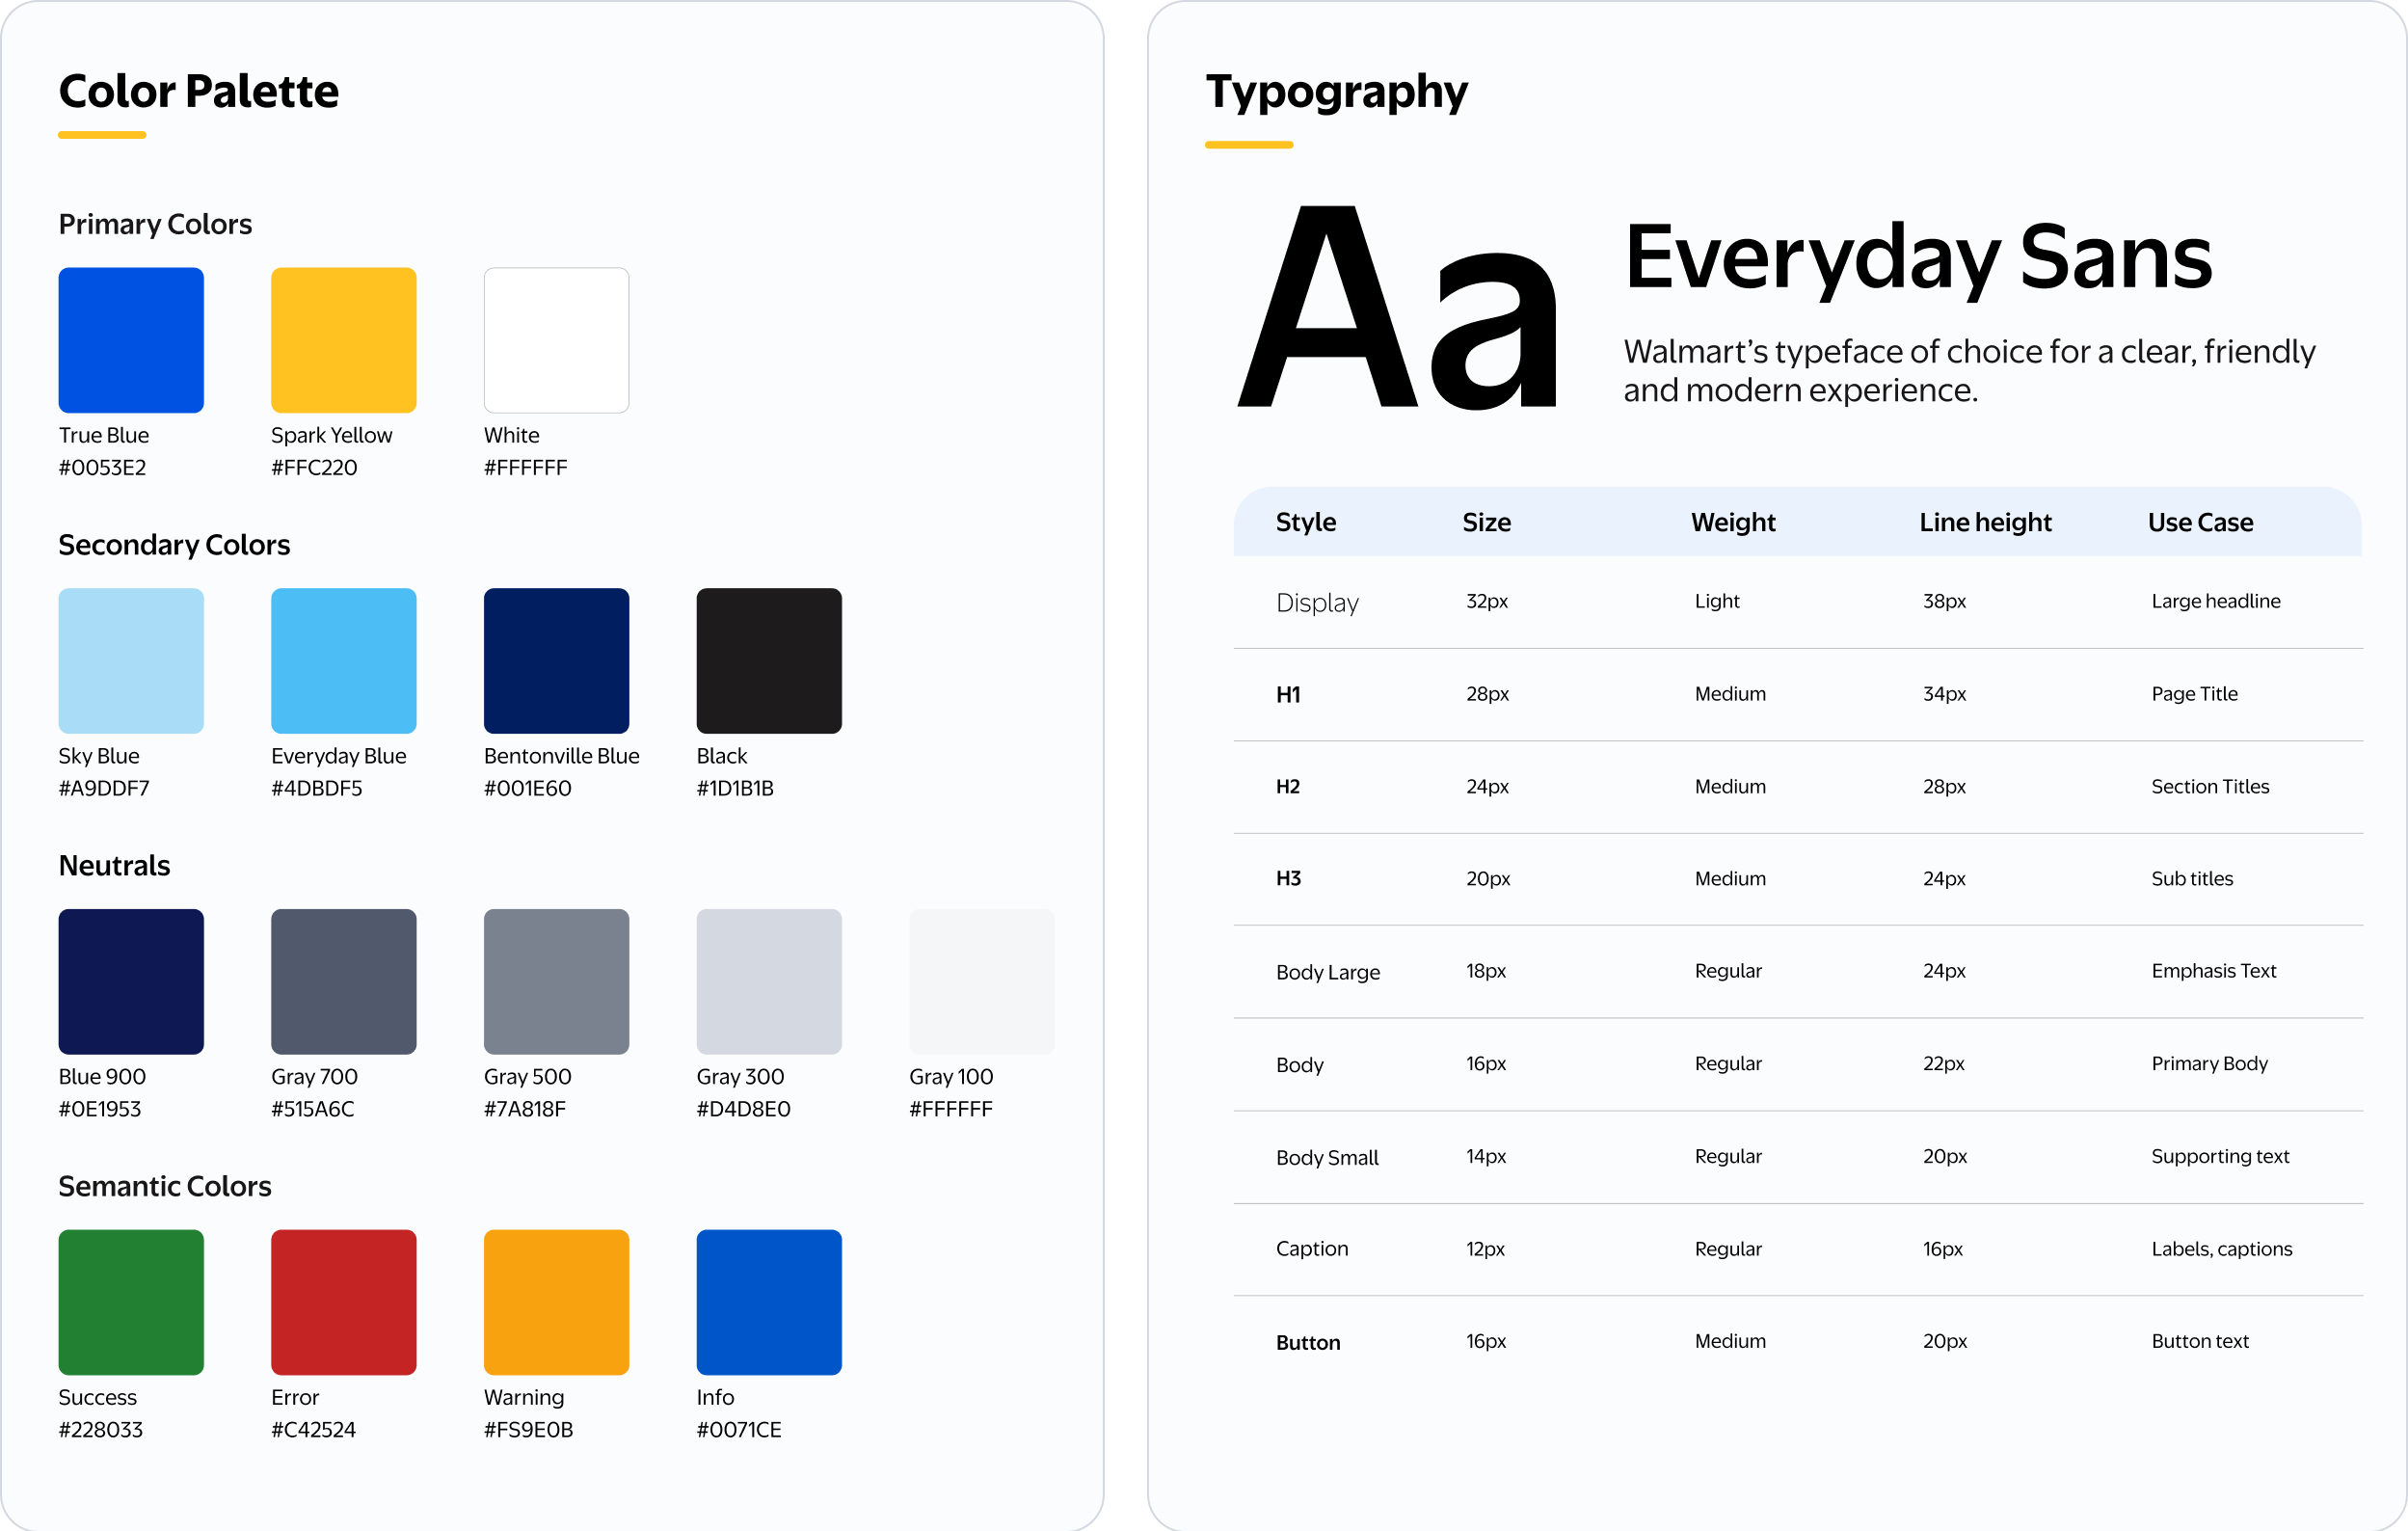
Color choices follow strict financial readability rules: True Blue commands primary navigation and affirmative actions, Spark Yellow highlights rewards and balance achievements, and Bentonville Blue anchors structure and high-contrast numerical typography.
A working prototype, not a flat set of frames.
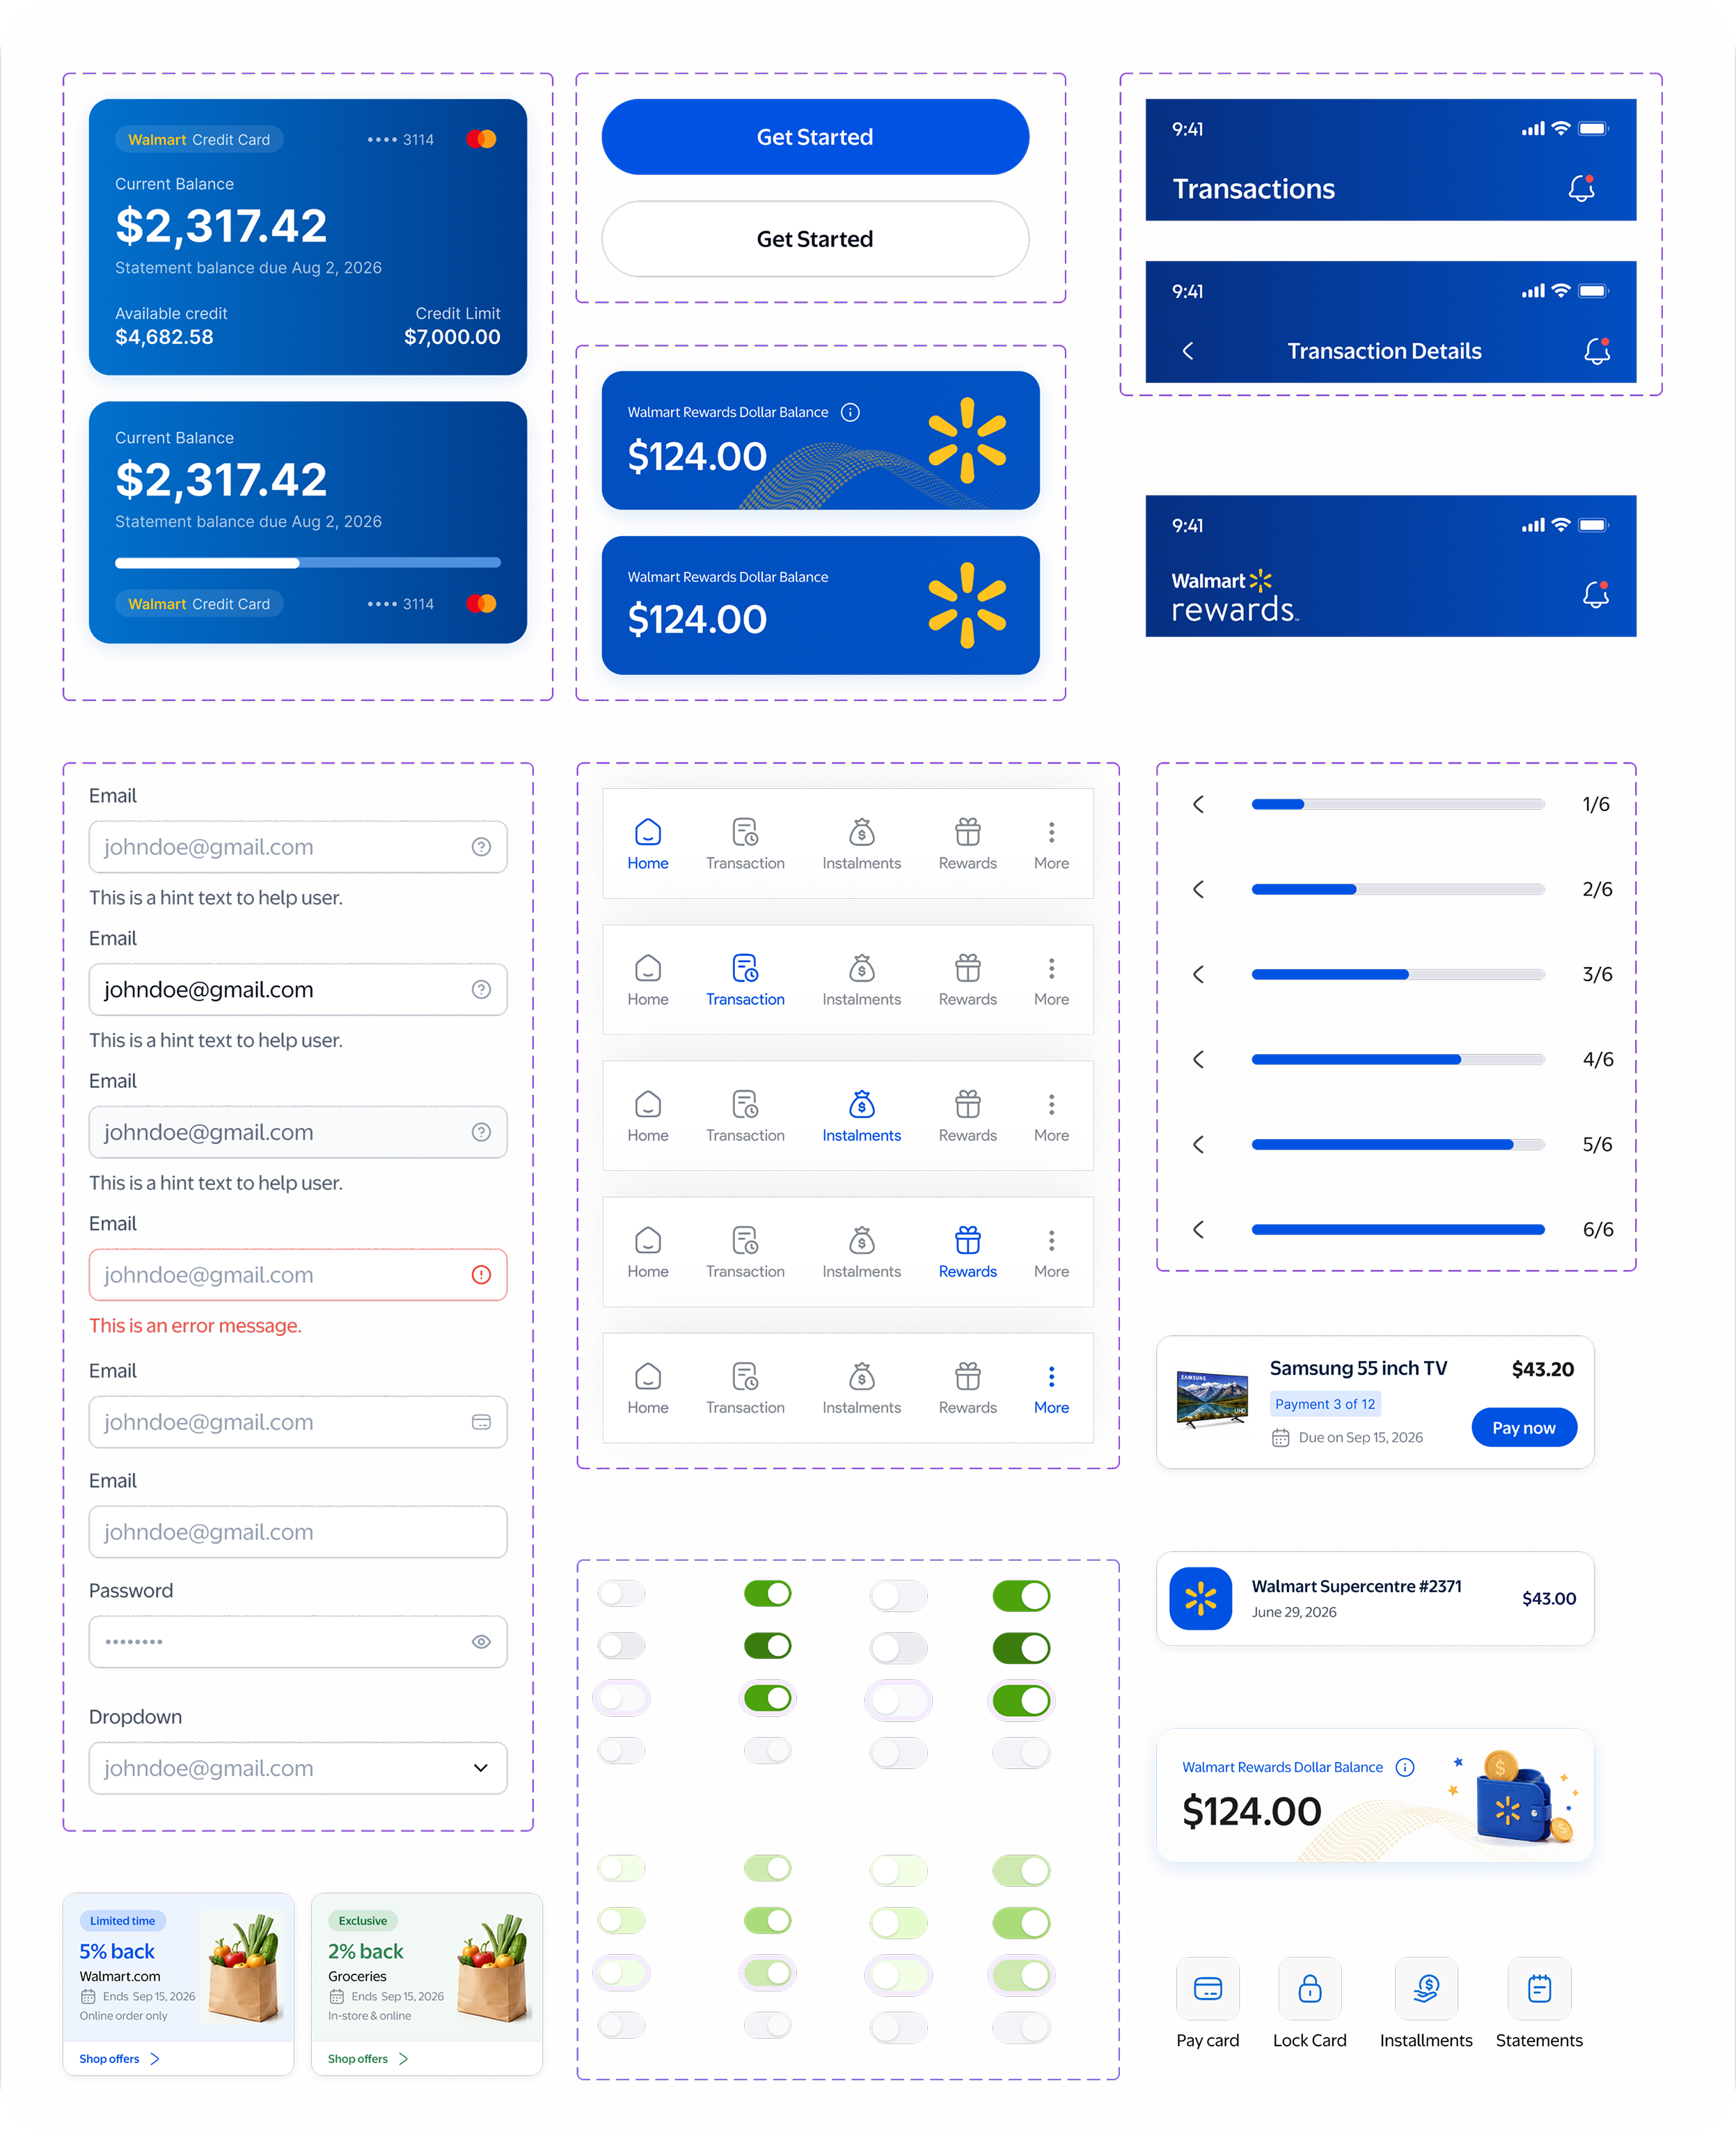
The visual language stays close to Walmart's own - blue for structure and action, yellow reserved for rewards and moments of attention, and clean white space so the balance is never competing with anything.


Four lessons that shaped how we'll build what's next.
Designing for a known brand raises the bar
Walmart's identity had to feel present without overwhelming financial UI conventions.
Benchmark past the obvious names
Six real apps, not just the market leaders, set a much clearer standard for what "modern" actually means here.
Real research makes a speculative concept credible
Grounding this in actual complaints and interviews made the problem framing far stronger than starting from assumptions.
MoSCoW makes scope concrete
It turned a long feature wish list into a clear, defensible first release.